How Can They Afford That House?
You see a neighbor move into a bigger home. A friend buys in a more expensive neighborhood. Someone you know makes an offer on a house you assumed would be way outside their budget.
And you wonder:
How can they afford that house?
The answer may be sitting in the home they already own.
For repeat homebuyers, home equity can become a powerful tool for making the next move possible. After years of paying down a mortgage while home values have grown, many homeowners have built up equity that can be turned into a substantial down payment on their next home.
And that can completely change the numbers.
Repeat Buyers Are Putting More Money Down
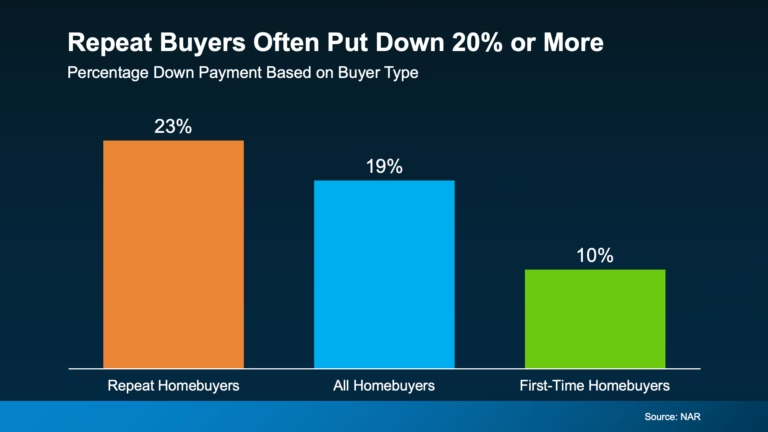
According to the National Association of Realtors, the typical repeat buyer puts down 23% when purchasing a home.
That is significantly more than many buyers put down when purchasing their first home.
Where is that money coming from?
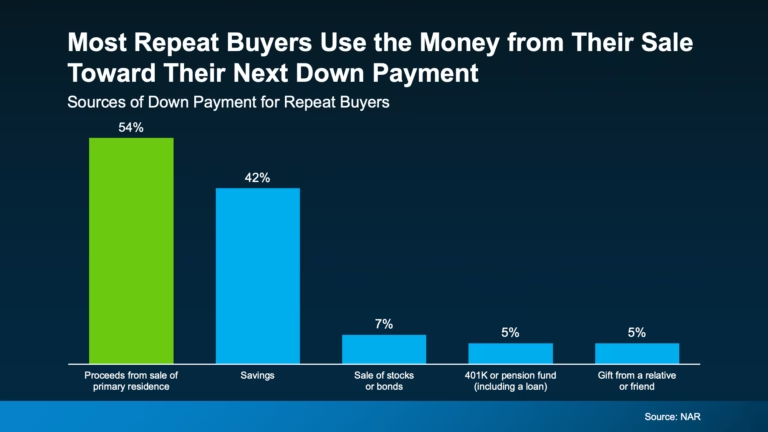
For many homeowners, it comes from the equity they have built in their current property.
Your equity is essentially the difference between what your home is worth and what you still owe on your mortgage.
Over time, two things can help that number grow:
- You continue paying down your mortgage balance
- Your home’s value may appreciate
When you sell your home, that equity can become cash that you may be able to use toward the purchase of your next property. That means the house you are living in today could help fund the house you want tomorrow.
You May Have More Buying Power Than You Realize
This is where homeowners sometimes underestimate their options.
You might look at today’s home prices or mortgage rates and immediately think moving is out of reach.
But before making that decision, it is worth looking at the entire financial picture.
If you have accumulated significant equity, you may be able to make a larger down payment. That could reduce the amount you need to finance and potentially make your next monthly payment much more manageable.
For some homeowners, the question is no longer simply:
“What would this new house cost me?”
A better question may be:
“What would this house cost me after I use the equity I’ve already built?”
Those can be two very different numbers.
What Could a 20% Down Payment Do for You?
You do not necessarily need to put 20% down to purchase a home. There are many financing options that allow qualified buyers to put down less.
But if your equity gives you the ability to put 20% or more down, there are some important advantages worth considering.
1. Lower Your Monthly Mortgage Payment
The larger your down payment, the less money you need to borrow.
Reducing the size of your mortgage can reduce your monthly principal and interest payment, which may help offset some of the impact of today’s interest rates.
2. Pay Less Interest Over Time
A smaller mortgage also means you are paying interest on a smaller amount of money.
That can translate into meaningful savings over the life of the loan.
3. Potentially Eliminate Private Mortgage Insurance
On many conventional loans, putting less than 20% down may require private mortgage insurance, commonly known as PMI.
Putting 20% down can typically eliminate that additional monthly expense.
4. Strengthen Your Overall Offer
A larger down payment may also help demonstrate strong financing when you are competing for a home.
Every transaction is different, but having substantial equity and strong financing can give you more options when structuring an offer.
Before You Decide You Can’t Move, Run the Numbers
This is the conversation I want more homeowners to have.
Do not assume that the price of your next home automatically makes moving unrealistic.
Your current home may have been quietly building the financial foundation for your next one.
If you have owned your home for several years, you may have considerably more equity than you realize. And that equity could potentially help you:
- Make a larger down payment
- Lower the amount you need to finance
- Reduce your monthly mortgage payment
- Avoid PMI
- Create more flexibility when shopping for your next home
The first step is simply finding out what the numbers look like for your situation.
Wondering How Much House Your Current Home Could Help You Buy?
Let’s look at your current mortgage, estimated home equity, potential sale proceeds and financing options together.
You may discover that your next home is closer than you thought.
Ready to run the numbers? Contact me to explore your options before you start shopping.